 Download slides
Ocean capacity remains available, but reliability is uneven
Published: giovedì, ottobre 01, 2026 | 09:00 CDT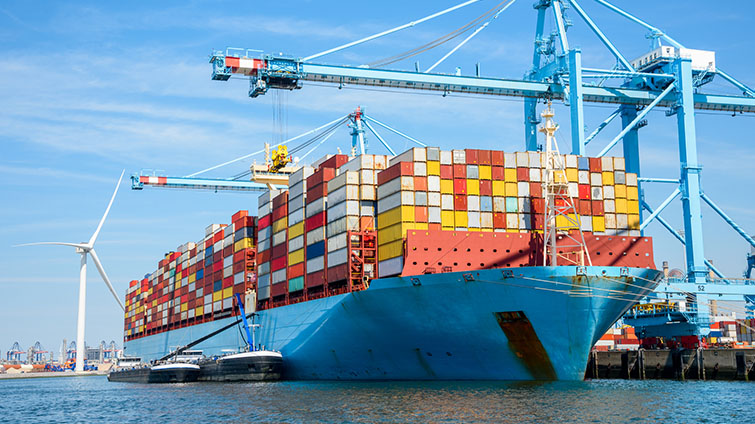
Aggiornato
Congestion and schedule disruption are limiting usable space
October begins with ocean markets following distinctly different paths. Trans-Pacific services are working through Golden Week capacity cuts, India–North America is affected by limited vessel space and disrupted connections at the Port of Colombo, while Asia–Europe is moving toward lower pricing as underlying supply improves.
It’s important to remember that all scheduled vessel capacity is not necessarily usable. Global port congestion is absorbing roughly 12% of vessel capacity—a four-year high—with significant impacts across East Asia, North Europe, and the Indian Subcontinent.
Schedule reliability has also fallen sharply as port congestion, vessel bunching, typhoons, Middle East conditions, and Panama Canal restrictions affect ocean networks.
For October, this creates a different planning problem than a conventional capacity shortage. Capacity may exist in the ocean network, but port congestion and steps the carriers are taking to get schedules back on track can change where and when that capacity is actually available.
Recent typhoons in Asia have led to carriers skipping ports, while congestion at transshipment hubs is changing connections and extending cargo backlogs. Full containers remain tied up at ports and empty containers are needing to be repositioned to meet demand in other markets.
Port omissions are particularly critical because the impact can occur after a shipment is already under way. A blank sailing around Golden Week can usually be accommodated in a booking plan before cargo moves.
A skipped port call or missed transshipment may require the container to wait for another feeder ship, move through a different hub, or be recovered through an alternate service after the original routing changes.
For shippers, October service decisions should therefore account for more than scheduled weekly capacity. Port selection, dependence on transshipping, container availability, and the ability to recover from a missed connection are becoming increasingly critical measures of whether capacity is actually usable.
Trans-Pacific conditions face a post-Golden Week test
Asia–North America enters October with tighter space and firmer pricing following the pre-Golden Week cargo push and planned blank sailings.
Those blank sailings during the October 1 through 7 holiday will continue reducing effective capacity through roughly mid-October, leaving the first post-holiday departures particularly exposed to rollovers as factories resume production and export volumes return.
How quickly that cargo returns will in part determine whether conditions extend further into the fourth quarter. A strong post-holiday rebound could keep preferred sailings full and sustain recent rate firmness, particularly on services already affected by reduced holiday capacity.
A slower recovery would allow space to normalize more quickly and could bring improved booking conditions in late October.
Recent typhoons closing some of China’s largest container ports could complicate that reset. That disruption contributed to vessel bunching and port omissions. Those in turn create cargo backlogs and alter transshipment locations, extending the impact beyond an individual disrupted sailing.
For shippers, that means post-Golden Week space availability will also be affected by whether ocean carriers have cleared the backlog and returned to their intended rotations.
The U.S. East Coast is expected to remain tighter than the West Coast, reflecting more limited service deployment and continued exposure to Panama Canal restrictions.
The previously planned October 1 draft reduction for Neopanamax vessels transiting the canal has been cancelled, removing one capacity concern that had been expected for the month. That would have lowered the amount of cargo the ships could carry.
Meanwhile, the number of ships allowed to transit daily dropped from 34 to 32 on September 15 and dependence on reservations can still affect schedule reliability. Missed transit windows remain a particular concern for Asia–U.S. East Coast services.
The first post-Golden Week sailings should provide the clearest indication of where the Trans-Pacific market is heading. Continued rollovers into mid-October would suggest that blank sailings, backlogs, and returning demand are keeping effective capacity constrained.
If those departures clear more quickly, booking conditions could loosen during the second half of the month even if published capacity changes little.
Asia–Europe rates are easing, but service conditions remain uneven
October is setting up differently on Asia–Europe lanes than on Asia-North America lanes. Pricing is softening into North Europe and the Mediterranean, and demand is expected to moderate after Golden Week. Ample vessel supply and the selective return of ocean service through the Suez Canal are also improving effective capacity.
Golden Week blank sailings may temporarily tighten individual departures and slow rate declines during the first half of the month, but do not indicate a structural capacity shortage. Unless the post-holiday demand rebound is stronger than expected, rates should continue to ease as October progresses.
North Europe port congestion remains the principal counterweight to improving that supply picture. Delayed vessels, terminal backups, and disrupted port rotations can still create missed connections or inconsistent transit times even as overall space becomes easier to secure. Rotterdam, Antwerp, and Hamburg are among the hotspots affecting global vessel schedules.
For October planning, the likely market direction is improved pricing with selective schedule risk rather than broad capacity tightness. Service-string differences will be most visible in port rotations, transshipment exposure, and the speed of recovery when congestion disrupts the published schedule.
India–North America remains one of the tighter origin markets
India–North America remains constrained heading into October, with strong demand and reduced vessel capacity continuing to limit booking flexibility. Incremental vessel capacity has been added, but it has not changed booking conditions, particularly into the U.S. East Coast and Gulf Coast.
The Port of Colombo in Sri Lanka remains a key pain point. Congestion across the Indian Subcontinent is already contributing to broader global schedule disruption, with Colombo, Nhava Sheva, and Mundra among the current congestion hotspots.
When mainline service strings omit or bypass Colombo to recover schedules, South India cargo can miss planned connections even when space is available on the onward vessel.
That distinction is particularly important for Tuticorin, Cochin, and Chennai cargo routed through Colombo. In these markets, the available main-vessel slot is only one part of the capacity equation. Feeder timing, container availability, dwell time during transshipping, and whether the mainline vessel makes its planned Colombo port call determine whether the container can use that space.
The result for October is greater rollover risk, longer booking lead times, and less ability to accommodate late production or purchase-order changes. Current conditions are expected to remain through at least mid- to late October, with limited evidence of near-term relief on U.S. East and Gulf Coast services.
For these origins, the October concern is not simply securing allocation; it is securing a routing whose feeder and mainline connections are likely to hold together. When delivery timing is critical, an alternate gateway or service with a more dependable connection may provide a better recovery path than waiting for space on a preferred sailing.
What could change the October outlook
A stronger-than-expected post-Golden Week rebound could keep Trans-Pacific sailings full longer, extend rollover pressure into the second half of October, and delay any easing in current rate conditions. Additional typhoon disruption or congestion at major Asian gateways could amplify that effect by pushing vessels further out of rotation.
On Asia–Europe, a broader and sustained return through the Suez Canal would add effective capacity and reinforce softer pricing. That outlook could shift if Red Sea conditions lead to renewed rerouting or if congestion at North European gateways continues to disrupt vessel schedules.
India–North America is less likely to improve quickly. Relief would require better feeder reliability through Colombo, fewer omitted calls, and more consistent equipment availability across South India origins.
Indicators to watch
- Rollovers on the first post-Golden Week Trans-Pacific sailings
- Port omissions and revised rotations at major Asian gateways
- Whether Trans-Pacific space normalizes after mid-October
- Additional Suez service restorations or renewed Cape routings
- Colombo feeder delays, missed connections, and omitted calls
- Equipment availability at Tuticorin, Cochin, and Chennai
- Panama Canal reservation delays affecting Asia–U.S. East Coast schedules
More service returns to the Suez Canal, but Middle East security concerns remain
More shipping lines are resuming service through the Suez Canal instead of diverting ships all the way around Africa’s Cape of Good Hope to get between Asia and Europe. Sea-Intelligence estimates that 27% of September Asia–Europe capacity in both directions is routing through the Red Sea and Suez Canal, although the return remains less advanced on Asia-to-Europe services.
Shorter round trips can release effective capacity without adding vessels, but the benefit remains service-specific and reversible if Red Sea conditions deteriorate.
A broader recovery would mean carriers using the Suez route consistently, publishing shorter transit times, accepting bookings on those services, and adjusting surcharges and vessel deployments accordingly.
Expect routing to remain inconsistent in the near term. One ocean carrier may offer a shorter Suez Canal service while another continues diverting around the cape. Shippers should verify the complete routing, connection points, and published schedule rather than assume that a quoted transit time reflects a broader return to Suez.
Regional security conditions, including military actions in the Middle East more generally and specifically in and around the Strait of Hormuz, remain an important watchpoint as carriers evaluate whether additional services can return safely and consistently.
Notable shifts this month
Trans-Atlantic westbound is improving, but recovery varies by gateway
North Europe–North America conditions are improving from the tighter environment seen in September, but the change is not uniform across destinations. Space into the U.S. East Coast is opening gradually, while U.S. Gulf and West Coast services remain more constrained.
Northern European gateways are also still working through schedule disruption and container imbalances carried over from summer congestion.
Conditions from the West Mediterranean are comparatively stable, although blank sailings, elevated port dwell time, and localized draft restrictions continue to affect individual services. Türkiye remains a tighter origin market, particularly for direct U.S. East Coast options.
Transshipment routings can provide additional capacity, but they introduce another connection point and greater exposure to schedule variability.
October is bringing more booking flexibility on some Trans-Atlantic services, but transit performance has not improved at the same pace. For shipments with firm delivery windows, direct-service availability and current gateway performance remain more useful than a broad assessment that Trans-Atlantic space is improving.
Canadian West Coast congestion is extending beyond the terminal
The primary Canadian West Coast concern in October is no longer wildfires disrupting rail transit to and from the ports. Instead, delayed vessel arrivals from Asia are contributing to vessel bunching at Vancouver and Prince Rupert, creating periods of heavier terminal activity that are carrying into the inland rail network.
For shippers, an on-time ocean arrival does not necessarily mean the cargo will continue on schedule. Terminal discharge time, rail availability, and inland legs should be incorporated into the expected transit time for West Coast routings during October, particularly for cargo with fixed delivery appointments or limited inventory coverage.
South America is gaining new gateway options
New service options through Puerto Antioquia and Cartagena are expanding alternatives for Colombia-bound cargo. The Port of Buenaventura, meanwhile, continues to face inland access and container-positioning challenges. For Peru, Chancay is broadening Pacific routing options.
The value of these alternatives will depend on final destination and inland requirements. For Colombia in particular, shifting gateways can change road travel time, transshipment exposure, container availability, and empty-container return requirements.
For October, the opportunity is greater routing flexibility, but the benefit will be shipment-specific rather than uniform.
Oceania remains stable as stink bug season progresses
Oceania lanes remain comparatively balanced between supply and demand entering October. Golden Week blank sailings may create short-lived rollover risk on some North Asia services, but vessel capacity remains broadly adequate.
Biosecurity requirements are becoming more relevant as the 2026–27 brown marmorated stink bug season moves into October. Australia applies seasonal measures to designated high-risk goods from target countries, while New Zealand requirements are concentrated on vehicles, machinery, and parts.
New Zealand authorities identify October through December as a particularly high-risk period for stink bug contamination.
For affected cargo, treatment requirements, timing, and documentation should be confirmed before shipment. A missed treatment requirement can create an arrival delay that available vessel space cannot resolve.
Planning ahead for October ocean freight shipping
Start October planning with full routing in mind, including connection points along the way and recovery options if the schedule changes.
1. Where is the routing most exposed to delay?
Review direct versus transshipment options, connection points, port rotations, and current schedule performance. An additional connection or congested gateway can increase the likelihood of missed sailings, a port omission, or extended transit time.
2. Is the booked capacity actually usable?
Confirm container availability, carrier allocations, cargo-weight acceptance, terminal cutoff times, and the current vessel rotation. A confirmed booking provides limited protection if the container cannot be positioned, accepted, or connected to the intended sailing.
3. What is the recovery path if the service changes?
Identify the next workable sailing, alternate gateway, transshipment option, or inland route before disruption occurs. Recovery options can narrow significantly once the container is already en route.
Additional planning considerations
- For Trans-Pacific cargo, watch the first post-Golden Week sailings closely. Rollovers into mid-October would indicate that holiday capacity reductions and returning demand are still limiting effective space.
- For India-origin cargo, evaluate feeder vessel reliability through the Port of Colombo in Sri Lanka and connection timing alongside main-vessel space. A mainline allocation is less valuable if the container cannot reliably make the connection.
- For Canada-bound freight through Vancouver and Prince Rupert, include inland rail performance in end-to-end transit expectations. Vessel bunching can continue affecting cargo after discharge.
- For services dependent on the Panama Canal, verify operating conditions and the planned routing, particularly for U.S. East Coast services where missed transit windows can affect downstream schedules.
- For Asia–Europe shipments, consider softer pricing alongside port rotation, transshipment exposure, and whether the service is routing through the Suez Canal or around Africa’s Cape of Good Hope.
 Approfondimenti utili sul trasporto merci